45 Critical Illnesses
A lump-sum benefit may be considered if the Person Covered is diagnosed with one of the 45 covered critical illnesses, subject to the certificate definitions and terms.
Critical Illness
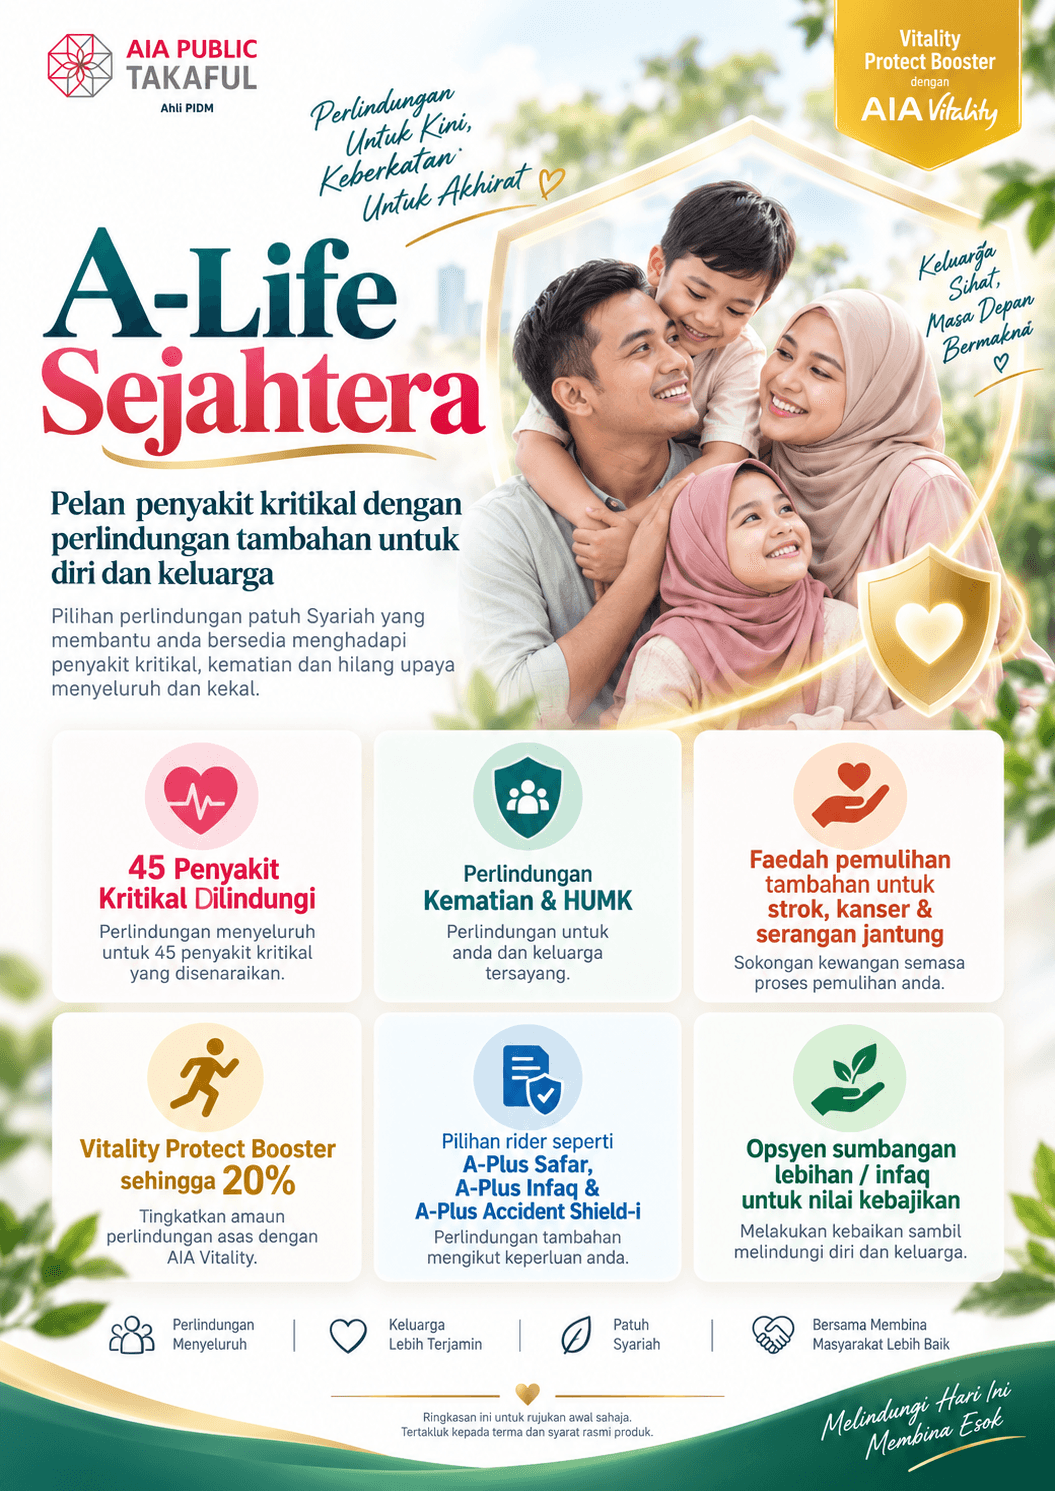
A-Life Sejahtera is a Shariah-compliant takaful plan that provides 3-in-1 protection for critical illness, death and Total and Permanent Disability (TPD), together with optional extra benefits that can be considered by need.
Basic Framework
The basic cover is structured around three main situations. This is the plan framework, not a promise that three full payouts can always be claimed separately.
A lump-sum benefit may be considered if the Person Covered is diagnosed with one of the 45 covered critical illnesses, subject to the certificate definitions and terms.
A death benefit is part of the basic structure and can support family financial planning, subject to nomination and the official documents.
TPD is included in the basic cover when the official definition is met, subject to terms, exclusions and underwriting.
A claim for the 45 critical illnesses, death or TPD may reduce the basic coverage amount. The certificate is usually terminated after 100% of the coverage amount has been claimed. For angioplasty and other invasive treatments for coronary artery disease, the amount payable is limited under the product terms.
Additional Benefit
The recovery benefit may be payable in addition to the basic cover if the Person Covered is diagnosed with one of the three stated conditions, subject to product eligibility.
Covered diagnoses for this benefit
01
20% of the basic coverage amount
The initial additional recovery percentage, subject to certificate terms.
02
+5% every 5 years
The percentage may increase according to the product schedule, not automatically without conditions.
This benefit applies only to the covered diagnoses and remains subject to waiting periods, medical definitions and the official documents.
AIA Vitality
Eligible AIA Vitality members may receive additional protection through Vitality Protect Booster when a covered claim occurs.
May apply to claims related to
Vitality Protect Booster applies only to AIA Vitality members. A higher status may offer more room for the benefit, up to the product maximum. This is not a guaranteed increase for every member.
Family
Besides critical illness, A-Life Sejahtera also includes death and TPD protection as part of its basic structure.
The death benefit can form part of family financial planning, subject to the relevant nomination, hibah or benefit-distribution arrangement.
This is not a hibah page. How a benefit is distributed depends on the official arrangement that is confirmed, not on a general assumption.
Options
A few optional riders may be considered with the basic plan. This is an early summary, not a full terms list.
Additional protection related to Hajj/Umrah and the related benefits stated in the product materials.
Additional protection that may be directed to charity or Waqf according to the selected arrangement.
More basic personal accident protection, subject to the rider scope.
More comprehensive personal accident protection than the basic option, subject to official terms.
A contribution waiver for a child's certificate under covered circumstances, subject to terms and the applicable illness list.
Charity
A-Life Sejahtera also leaves room for charitable value through surplus donation and the A-Plus Infaq rider.
At a Glance
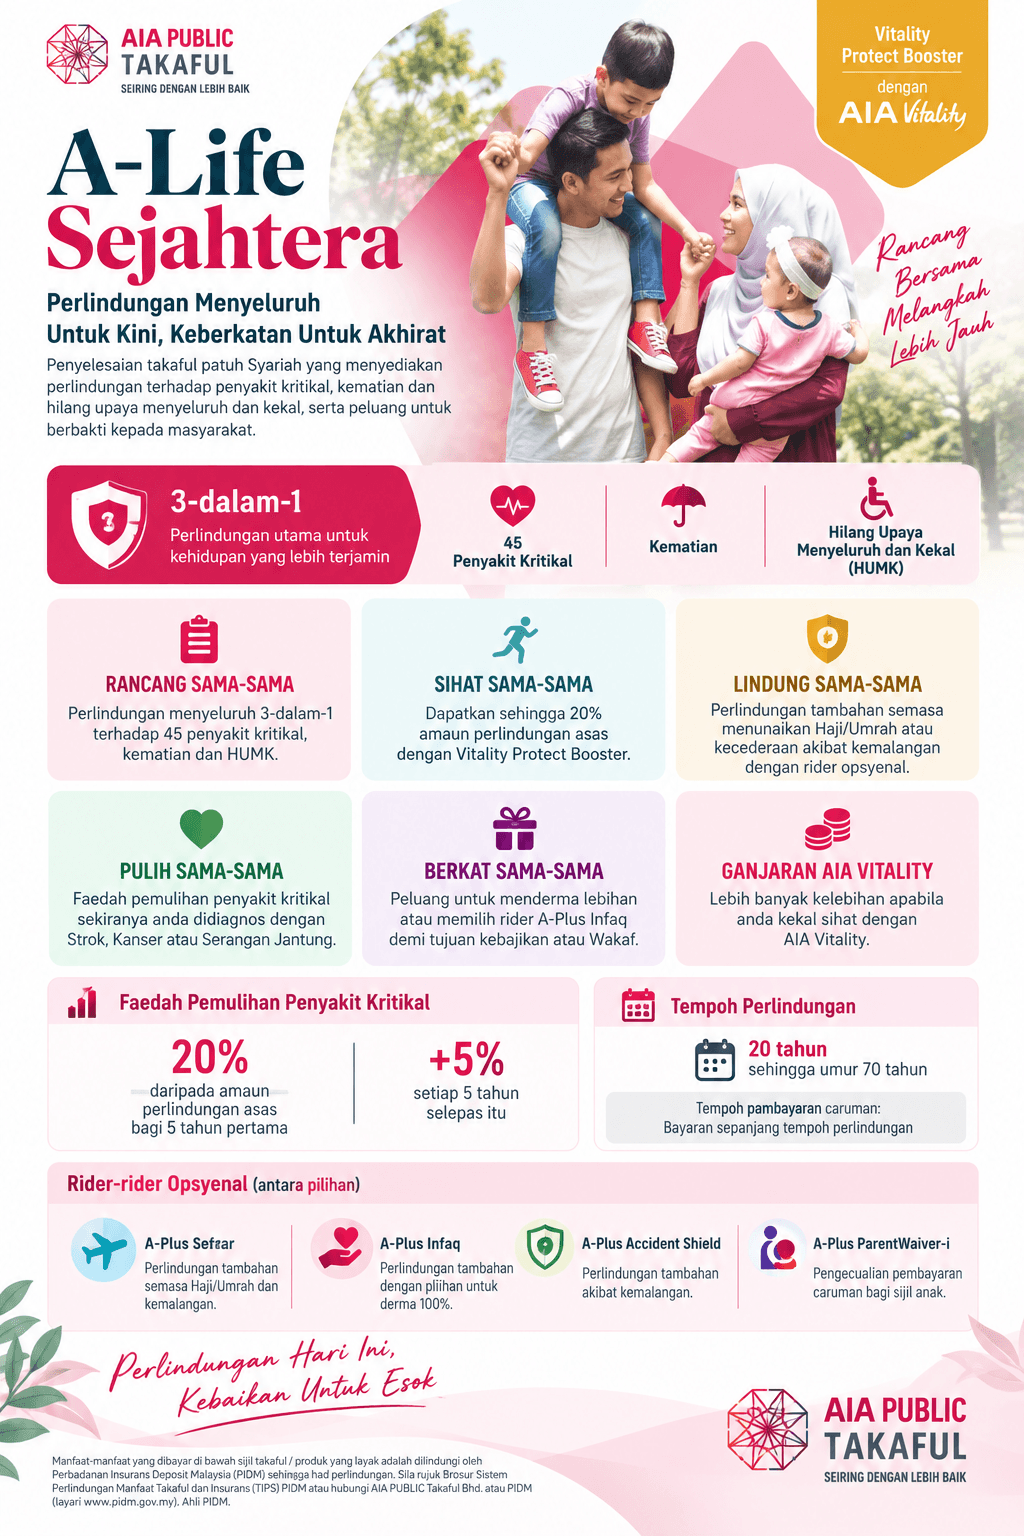
This visual summary is provided to make the first reading easier. Actual benefits remain subject to terms, conditions, exclusions, waiting periods and the official product documents.
Covered List
These are the medical names of the 45 critical illnesses stated in the brochure. Each diagnosis remains subject to the definitions, severity and exclusions in the certificate.
These names are an early reference. Full definitions, covered stages and waiting periods must be read in the official documents. For A-Plus ParentWaiver-i, angioplasty is not included in the covered list.
This information is a summary for early explanation only. Actual benefits are subject to terms, conditions, exclusions, waiting periods, underwriting and the official product documents.